The Cardano Foundation has launched CIP-0113, a programmable token standard that allows issuers of stablecoins, tokenized funds, bonds and other regulated assets to embed compliance rules directly into their tokens. The standard is now live on the Cardano mainnet, following independent security audits. It can enforce KYC and AML requirements, sanctions screening, transfer restrictions, and issuer-controlled freeze and seizure functions whenever a programmable token is transferred, minted or burned.
Cardano Adds Programmable Token Controls
Traditional Cardano native tokens can generally move between addresses without issuer-level transfer restrictions. That creates a problem for financial institutions issuing regulated assets on a public blockchain because compliance rules may require assets to remain with verified investors or be blocked from sanctioned addresses.
CIP-0113 addresses that limitation by attaching programmable logic to the asset. The Cardano token standard requires a successful validation script before ownership changes, allowing issuers to determine which transfers are permitted.
The framework can support several compliance functions:
- KYC and AML: Restrict transfers to approved participants.
- Sanctions screening: Block transfers involving restricted addresses.
- Freeze and seize: Allow authorized actions when legal or regulatory rules require them.
The Foundation says issuers can select existing rule modules or create customized logic as requirements change.
CIP-0113 Works Without a Hard Fork
The design uses Cardano’s existing extended UTXO (EUTXO) architecture and does not require a hard fork. Programmable tokens remain native Cardano assets, while the additional validation layer determines whether transfers, minting and burning operations satisfy the token’s rules.
The architecture places programmable tokens under a shared smart-contract framework. Transactions are checked against the relevant rules before the ledger accepts them. This means compliance conditions travel with the asset rather than relying solely on individual exchanges, wallets or applications to enforce them.
The model is particularly relevant to tokenized real-world assets, including regulated securities and funds. However, holders should understand that certain tokens may carry powers that ordinary cryptocurrencies do not. Depending on the rules selected by an issuer, an authorized party can potentially freeze, seize or forcibly transfer assets without the holder’s consent.
Cardano Targets Regulated Tokenization
The launch places Cardano alongside networks that already support restricted or permissioned token structures. Ethereum has standards such as ERC-3643, while Solana supports transfer-control features through its Token Extensions. The XRP Ledger also provides issuer controls for certain tokens.
Cardano’s implementation is designed to give these controls a standardized framework across wallets, explorers and decentralized applications. The Foundation has identified Eternl, Gero Wallet, CardanoScan and BloxBean among the tools supporting the launch.
The standard has also received recognition under the certification framework of the Capital Markets and Technology Association (CMTA), a Swiss industry organization involved in standards for tokenized financial assets.
Conclusion
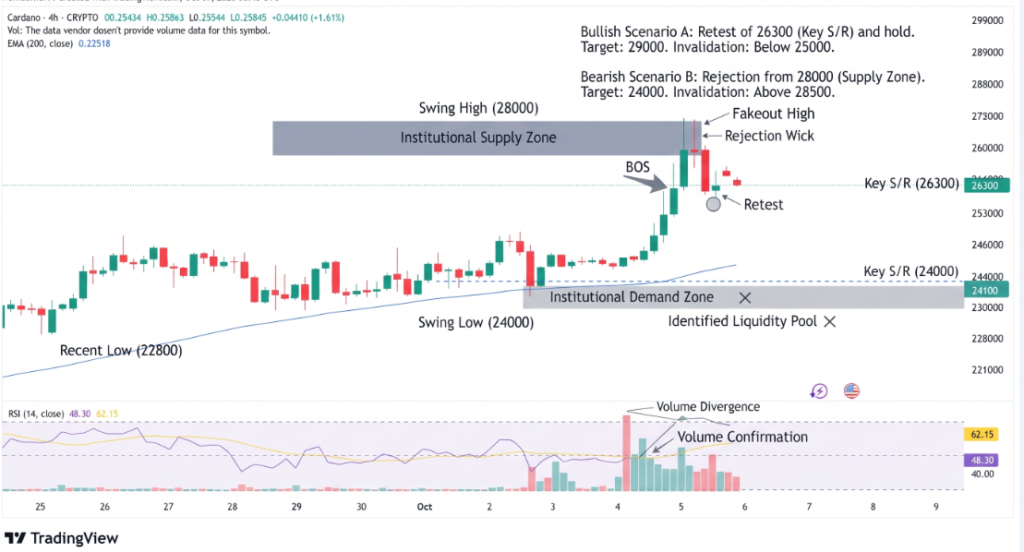
CIP-0113 gives Cardano issuers a more structured way to bring regulated assets onchain while retaining issuer-level compliance controls. The ability to enforce KYC, sanctions checks, transfer restrictions and freeze-or-seize rules could make the network more suitable for institutional tokenization. The trade-off is clear: holders of programmable assets may accept restrictions and issuer powers that do not exist with conventional freely transferable tokens. Meanwhile, ADA has fallen alongside the broader crypto market, keeping the token’s near-term performance separate from the longer-term implications of the new standard.
Sources & Methodology
Primary-source standard: Market-moving facts should link to original data releases, regulator notices, company filings or official project announcements whenever available. Secondary reporting is used for additional context, not as a substitute for original evidence.
Page last reviewed: