U.S. stock futures were mixed Sunday evening as investors weighed a stronger-than-expected August jobs report that raised the odds of a Federal Reserve rate hike, with trading expected to stay thin ahead of Monday’s Labor Day holiday. Dow Jones futures fell 0.5% to 53,196.0 points, S&P 500 futures eased 0.1% to 7,718.25, and Nasdaq 100 futures rose 0.3% to 29,640.0 by 06:24 GMT. The moves followed a weak Friday session after the jobs data reshaped the Fed’s rate outlook.
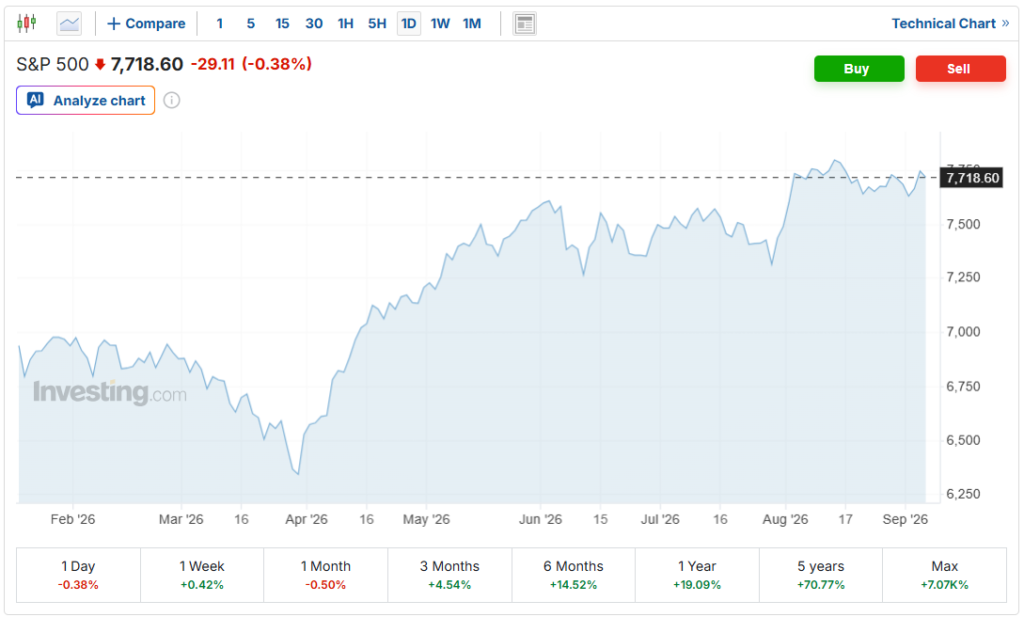
Source: investing.com
August Payrolls Crush Forecasts
The Bureau of Labor Statistics reported Friday that nonfarm payrolls rose by 162,000 in August, nearly three times the roughly 53,000-to-56,000 gain economists had forecast and the strongest monthly increase since March. The unemployment rate held at 4.1%, while labor-force participation rose 0.2 percentage point to 61.6% as 683,000 people entered the workforce. Payroll figures for June and July were revised up by a combined 55,000 jobs, with July’s initially reported 23,000 decline turning into a 21,000 gain. Average hourly earnings climbed 0.3% to $37.75, up 3.1% over the past year. Job gains concentrated in food services and drinking places, up 59,000, and local government education, up 42,000, while the information sector lost jobs.
Fed Hike Odds Climb to 62%
The stronger reading reversed much of the easing sentiment that had supported equities in recent weeks. Interest-rate futures implied roughly a 60%-to-62% probability of a 25-basis-point hike at the Fed’s Sept. 15-16 meeting, up from about 49%-55% before the report, according to CME FedWatch data. Wall Street’s major indexes fell Friday in response, with technology and semiconductor stocks holding up better than the broader market:
- The Dow Jones Industrial Average lost 0.5%, the S&P 500 declined 0.4%, and the Nasdaq Composite shed 0.3%
- Consumer discretionary stocks underperformed, while technology and semiconductor names were comparatively resilient
Inflation Data Now Takes Over
Attention now shifts to this week’s inflation reports, with the producer price index due Thursday and the consumer price index following Friday, ahead of the Sept. 15-16 FOMC meeting. Fed officials, including Governor Christopher Waller, have said they would support holding rates steady if upcoming data confirms disinflation continues, while Fed Chair Kevin Warsh has struck a more hawkish tone since his Jackson Hole remarks. New York Fed President John Williams described the central bank’s approach as data-dependent. U.S. cash equity markets will be closed Monday for Labor Day, with regular trading resuming Tuesday; the holiday-shortened week could leave markets more sensitive than usual to moves in Treasury yields, oil prices, and shifting Fed expectations.
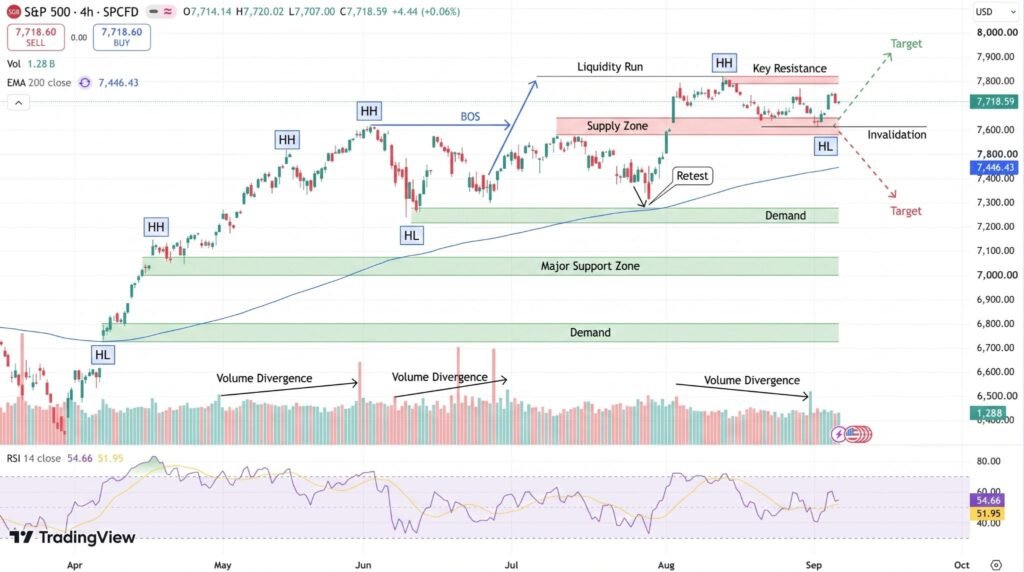
SPX Price Chart – Source: Tradingview
Conclusion
Friday’s payroll surprise did what months of Fed commentary could not: it flipped the market’s rate debate from whether the Fed might ease to whether it might tighten, lifting hike odds from roughly 50% to above 60% in a single session. With cash markets closed for Labor Day and this week’s producer and consumer price reports standing between Wall Street and the Sept. 15-16 decision, a holiday-thinned market now has to digest a genuinely two-sided rate outlook rather than the one-directional easing story that had carried stocks through most of the summer.
Sources & Methodology
Primary-source standard: Market-moving facts should link to original data releases, regulator notices, company filings or official project announcements whenever available. Secondary reporting is used for additional context, not as a substitute for original evidence.
Page last reviewed: