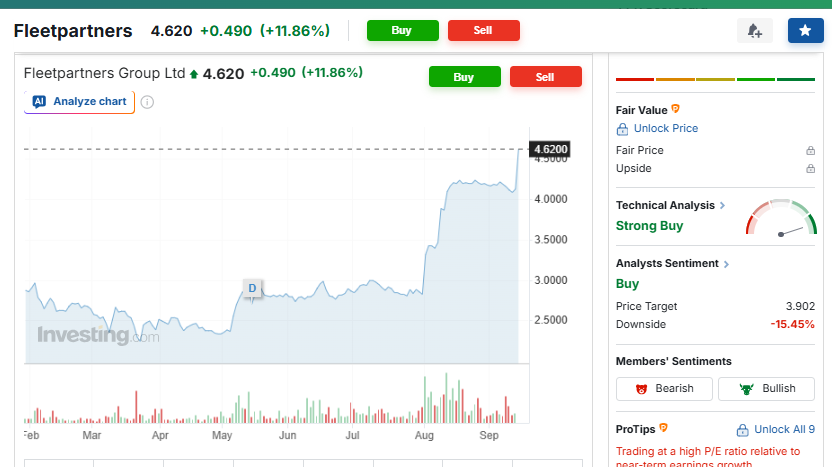
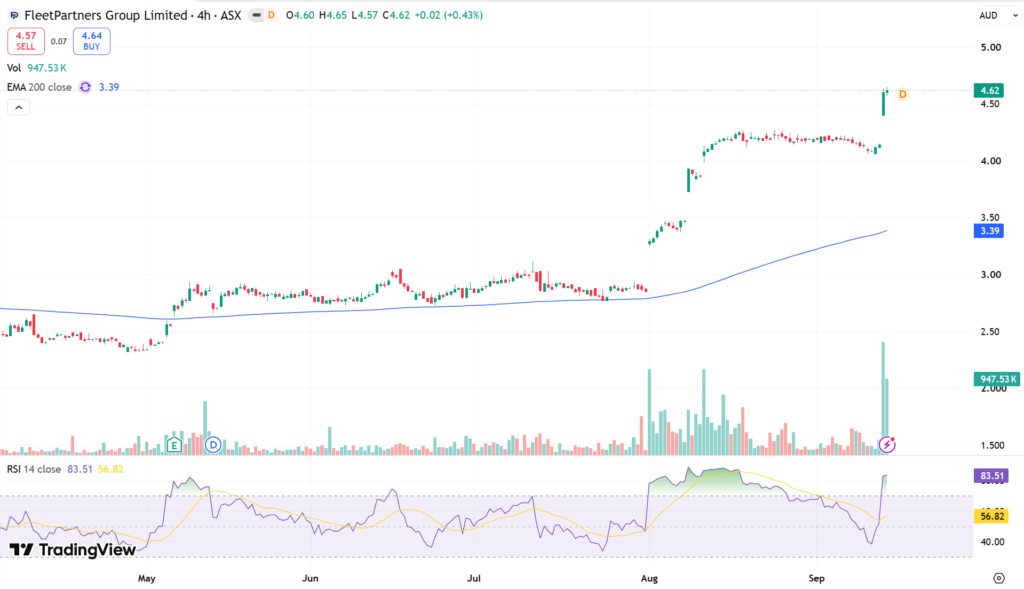
FleetPartners Group shares surged 12.35% to a record A$4.64 on Monday as three bidders raised their takeover offers for the Australian vehicle leasing company, pushing its valuation close to A$1 billion. The stock has risen about 64% from its July 31 close of A$2.83 before the auction began, far outpacing the S&P/ASX 200’s modest 0.05% gain to 8,746.00, as reported by Reuters.
FleetPartners Receives Raised Bids of Up to A$4.65 as Element Fleet Exits Auction
FleetPartners confirmed it received revised non-binding proposals from SG Fleet (backed by Pacific Equity Partners), Japan’s ORIX Corp, and a consortium led by Sumitomo Corp. ORIX and the Sumitomo group each offered A$4.65 per share, valuing the company at approximately A$982.1 million (about US$702 million). SG Fleet raised its bid to A$4.55 per share. These represent premiums of 10.2% and 12.6% respectively to the previous Friday’s close. The new offers top SG Fleet’s prior leading bid of A$4.00 (valuing the firm at A$844.8 million).
The board has granted all three remaining bidders further due diligence access. No proposals are binding, and no transaction has been agreed. Canada’s Element Fleet Management withdrew after completing Phase 1 review, citing that continuing in the competitive process did not offer a compelling risk-adjusted return. The bidding began in early August with SG Fleet’s initial A$3.60 proposal, followed by Element and ORIX at A$3.80, SG Fleet’s lift to A$4.00, and the Sumitomo consortium’s A$3.85 entry.
Strong Investor Confidence in Premium Takeover Fuels FleetPartners Share Rally Near Top Bid
The sharp rise reflects investor confidence that the competitive auction will deliver a premium exit near or above the latest indicative values. Shares traded just one cent below the A$4.65 offers, signalling strong market pricing of a potential deal. The strategic value of FleetPartners’ novated leasing business—where employees salary-sacrifice vehicle costs—has drawn international interest from established fleet players seeking scale in Australia and New Zealand. Strong recent operational momentum, including upgraded guidance, further supported the re-rating amid an otherwise flat broader market.
FleetPartners Posts A$25.8m Novated EBITDA (+28%), A$2.4bn AUMOF and Upgraded FY26 Outlook
FleetPartners is a major provider of vehicle leasing, fleet management and salary packaging across Australia and New Zealand. Its novated segment contributed nearly a fifth of operating earnings in fiscal 2025, delivering A$25.8 million EBITDA (up 28% year-on-year from A$20.2 million). Assets under management or financed (AUMOF) rose about 2% to A$2.3 billion in FY25, with later updates showing further growth to around A$2.4 billion. Group core income reached A$169 million (up 6%), while overall FY25 EBITDA was A$132.4 million. A recent quarterly update highlighted novated leasing growth of 20% year-to-date, group core income up 7%, and an upgraded FY26 new-business-writing outlook to high-single-digit growth. The segment has benefited from incentives for eligible electric vehicles. The company has also completed operational improvements, including systems upgrades that delivered cost savings, making it a cleaner target for strategic buyers.
FleetPartners Bidding Process Advances to Due Diligence as Three Suitors Remain
The three remaining bidders will progress through the next phase of due diligence. FleetPartners has emphasised that the proposals remain non-binding and conditional, with no certainty of a transaction. Further revised offers, exclusivity requests, or a preferred bidder recommendation from the board could emerge in the coming weeks. Shareholders will watch for any binding scheme implementation deeds or competing proposals. Element’s exit narrows the field but leaves strong Japanese and domestic private-equity-backed interest. Broader market conditions, interest rates, and any regulatory clearances required for a cross-border deal will also influence the timeline and final outcome.
Sources & Methodology
Primary-source standard: Market-moving facts should link to original data releases, regulator notices, company filings or official project announcements whenever available. Secondary reporting is used for additional context, not as a substitute for original evidence.
Page last reviewed: