The US Dollar Index (DXY) closed at 102.11, gaining 0.51%, as investors shifted their attention from stronger-than-expected U.S. employment figures to a new round of inflation data. Deutsche Bank strategist Jim Reid and his team say October’s Consumer Price Index (CPI) and Producer Price Index (PPI) reports will help shape expectations for the Federal Reserve’s next policy decisions. Although the bank expects monthly inflation to moderate, it continues to forecast two additional 25-basis-point rate increases.
Dollar Gains as Fed Outlook Supports It
The dollar has drawn support from resilient U.S. economic data and expectations that the Federal Reserve may maintain a restrictive monetary stance for longer. Strong payroll figures have reinforced the view that the economy can withstand higher borrowing costs, while investors now await inflation readings for further evidence.
According to Deutsche Bank, economists expect headline CPI to increase 0.20% month-on-month in October, down from 0.65% in the previous reading. Core CPI, which excludes food and energy prices, is also forecast to rise 0.20%, compared with 0.33% previously.
The figures matter because inflation that remains persistent could strengthen the case for further monetary tightening. Conversely, softer readings could temper expectations for rate increases and potentially limit the dollar’s upside.
The Federal Reserve will also be in focus as several policymakers are scheduled to speak. Their comments could provide additional clues about how officials assess inflation risks, employment conditions and the appropriate path for interest rates.
Missing CPI Data Complicates Inflation Picture
October’s inflation report carries an unusual statistical limitation. The Bureau of Labor Statistics did not produce October 2025 index levels for many CPI series because of the federal government shutdown. Consequently, year-over-year comparisons for affected categories cannot be calculated in the October 2026 release.
This does not prevent the publication of monthly inflation changes, but it removes an important measure that investors and policymakers normally use to assess the broader inflation trend.
Attention will then turn to October PPI, scheduled for Friday, November 13. Deutsche Bank expects producer prices to increase 0.20% month-on-month, easing from 0.32% in September. The bank sees the annual producer inflation rate remaining broadly steady at 3.1%.
- Headline CPI forecast: 0.20% monthly growth.
- Core CPI forecast: 0.20% monthly growth.
- PPI forecast: 0.20% monthly growth.
- Annual PPI forecast: Approximately 3.1%.
Deutsche Bank Sees Two More Fed Hikes
Despite its expectation of softer monthly inflation, Deutsche Bank continues to forecast 25-basis-point rate increases in December and March. The bank says this outlook remains in place unless financial conditions tighten materially further.
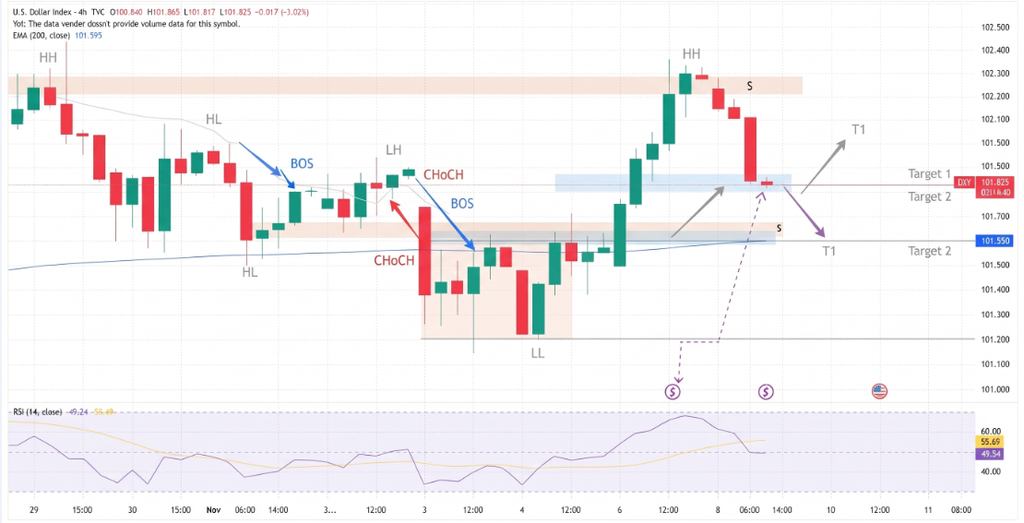
A 25-basis-point increase represents a quarter of a percentage point. Further hikes would raise borrowing costs across the economy and could support the dollar by making U.S. assets more attractive to international investors.
Conclusion
The Dollar Index’s 0.51% advance to 102.11 reflects continued support from resilient economic data and expectations of further Federal Reserve tightening. However, the October CPI report and Friday’s PPI figures could alter the market’s assessment of the policy outlook. Softer inflation may challenge the dollar’s momentum, while stronger readings could reinforce Deutsche Bank’s forecast for two additional rate increases. Investors will therefore watch the monthly data and Fed commentary closely for the next directional signal.
Sources & Methodology
Primary-source standard: Market-moving facts should link to original data releases, regulator notices, company filings or official project announcements whenever available. Secondary reporting is used for additional context, not as a substitute for original evidence.
Page last reviewed: