Holding cryptocurrencies through market cycles has generated substantial returns for some investors, but XRP has struggled to deliver the same long-term performance as Bitcoin and Ethereum. At around $1.33, XRP remains approximately 62.5% below its January 2018 peak of $3.55. Although the token briefly surpassed that record in July 2025, its subsequent decline has renewed questions about supply growth, investor demand, institutional participation and the business priorities of Ripple, the company closely associated with the asset.
XRP Supply Growth Limits Price Recovery
One major difference between XRP and other leading cryptocurrencies is the growth in its circulating supply. According to data cited by research firm Nansen, XRP’s circulating supply increased from 38.7 billion tokens in 2017 to 63.1 billion, a rise of approximately 63%.
When more tokens circulate, each token represents a smaller share of the asset’s overall market capitalization, assuming total market value remains unchanged. This helps explain why XRP’s price has struggled to revisit its previous peak despite the expansion of the broader cryptocurrency market.
Oliver Carding of institutional digital-asset manager Tesseract Group argued that market capitalization provides a more useful comparison than token price alone. With substantially more XRP circulating today, the market would need to assign the asset a significantly higher total valuation for its price to regain the 2018 record.
Other major cryptocurrencies have performed better over the same comparison period:
- Bitcoin (BTC): Up approximately 314% from its December 2017 peak of $19,804.
- Dogecoin (DOGE): Up approximately 322% from its January 2018 high.
- BNB: Up roughly 2,800% from its early-2018 level.
- Ethereum (ETH): Up approximately 66% from its December 2017 peak.
These comparisons use historical price snapshots and do not account for differences in token supply or risk.
ETF Demand and Trading Activity Lag
Institutional access has expanded through exchange-traded funds (ETFs), but XRP products have attracted less capital than established Bitcoin and Ethereum funds. According to SoSoValue, cumulative net inflows into US-listed XRP funds reached approximately $1.8 billion by October 2026. That represents meaningful demand, although comparisons with larger crypto markets remain challenging.
Nansen data cited in the report also indicated declining activity, with XRP spot trading volume down 53.5%, perpetual futures volume lower by 44% and active addresses falling 10.7%.
Ripple has concentrated on cross-border payments, institutional infrastructure, its RLUSD stablecoin and trade finance rather than competing directly across every major crypto investment theme. That strategy may support real-world utility, but it does not automatically translate into sustained demand for XRP itself.
Regulatory History Still Shapes Sentiment
The SEC’s lawsuit against Ripple, filed in December 2020, created years of uncertainty. In 2023, a federal court distinguished between XRP sales to institutional investors and certain programmatic exchange sales. The appeals ended in August 2025, leaving the final judgment and a $125 million civil penalty in place.
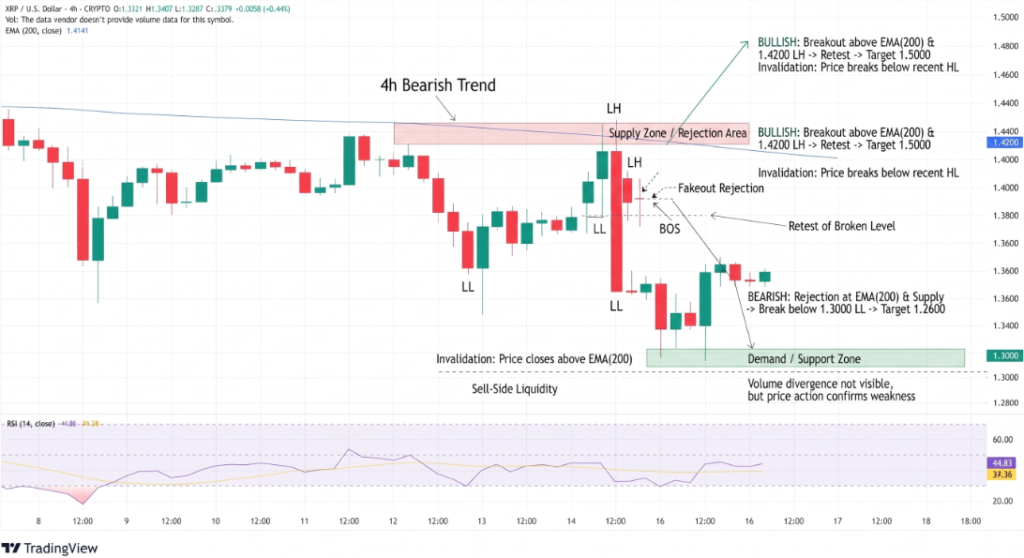
Although the case has concluded, XRP’s relative performance remains a concern for long-term holders.
Conclusion
XRP’s underperformance reflects several overlapping factors: a larger circulating supply, weaker trading activity and less institutional capital than Bitcoin and Ethereum attract. Ripple’s payment-focused strategy may create opportunities, but sustained token appreciation depends on demand keeping pace with supply. Investors should monitor XRP’s performance against Bitcoin, changes in circulating supply and fund flows to assess whether the asset’s long-term outlook is improving.
Sources & Methodology
Primary-source standard: Market-moving facts should link to original data releases, regulator notices, company filings or official project announcements whenever available. Secondary reporting is used for additional context, not as a substitute for original evidence.
Page last reviewed: