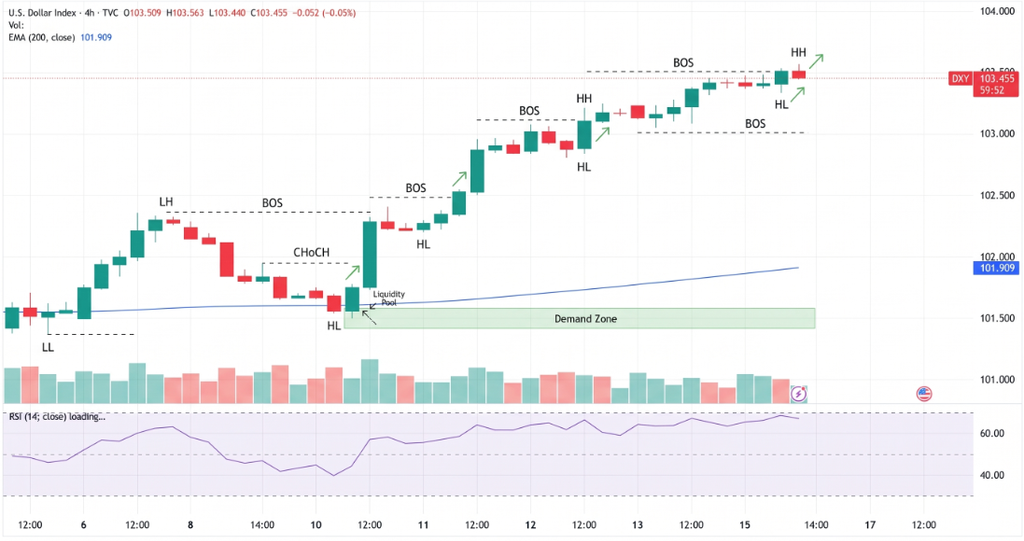
The US Dollar Index (DXY) climbed toward 103.50 on Monday, November 16, extending last week’s advance as stronger inflation data and hawkish Federal Reserve comments encouraged investors to anticipate further monetary tightening. The index reached a fresh 2026 high, trading near its strongest level since April 2025. Rising Treasury yields have added support to the greenback, while markets increasingly consider the possibility of consecutive interest-rate increases beginning in December. Attention is now shifting toward upcoming Fed speeches and the minutes of the October policy meeting.
Fed Rate Expectations Drive Dollar Higher
The latest dollar rally reflects a significant reassessment of the Federal Reserve’s monetary-policy outlook. MUFG analyst Lee Hardman attributes the move to three consecutive upside surprises in US core consumer inflation and increasingly hawkish comments from central bank officials.
October’s core Consumer Price Index (CPI), which excludes volatile food and energy prices, increased 0.3% month over month. The reading reinforced concerns that inflation remains persistent rather than moving consistently toward the Fed’s 2% target.
Fed Governor Christopher Waller said a 25-basis-point increase would be appropriate in December if inflation develops as expected. However, he also indicated that a 50-basis-point increase should be considered if monthly core inflation remains around 0.3% or higher.
According to the supplied CME FedWatch snapshot, traders assign approximately a 9% probability to a half-percentage-point December increase. Meanwhile, MUFG highlights growing expectations for three consecutive quarter-point increases in December, January and March.
Such a sequence could lift the effective federal funds rate toward 4.6%, strengthening the dollar’s yield advantage against currencies backed by less restrictive monetary policies.
Treasury Yields Reinforce Dollar Strength
Higher US bond yields have provided another source of support for the greenback. The two-year Treasury yield, which is particularly sensitive to expectations for Federal Reserve policy, has approached 4.85%, while the benchmark 10-year yield has remained near 5.13%.
The latest market figures highlight the extent of the repricing:
- DXY: Trading around 103.50, its highest level since April 2025.
- Two-year Treasury yield: Approximately 4.85%.
- Ten-year Treasury yield: Approximately 5.13%.
- December half-point hike probability: Around 9%, according to the supplied CME snapshot.
Meanwhile, oil prices remain sensitive to developments in the Middle East. Although recovering exports have eased some supply concerns, persistent US-Iran tensions could generate renewed energy-price pressure and complicate the inflation outlook.
Fed Speeches and Minutes in Focus
Kansas City Fed President Jeff Schmid reinforced the hawkish message on Sunday, saying inflation remained uncomfortably above the central bank’s 2% objective and was moving in the wrong direction. He argued that policymakers still had work to do to restore price stability.
Investors are now monitoring comments from New York Fed President John Williams and Fed Chair Kevin Warsh for further guidance on the policy outlook. The October 27-28 FOMC meeting minutes, scheduled for November 18, could also reveal how strongly policymakers are considering additional increases.
Conclusion
The US Dollar Index remains supported by persistent inflation, rising Treasury yields and expectations of further Fed tightening. A sustained move above 103.50 could reinforce bullish momentum, while softer inflation signals or less hawkish central bank comments could trigger a correction. The upcoming Fed communications will be crucial in determining whether the dollar can extend its advance.
Sources & Methodology
Primary-source standard: Market-moving facts should link to original data releases, regulator notices, company filings or official project announcements whenever available. Secondary reporting is used for additional context, not as a substitute for original evidence.
Page last reviewed: